

Recently, leading foreign investment banks, including JP Morgan, Goldman Sachs and UBS, have issued research reports expressing a distinctly positive outlook on China's A-share market, where shares of Chinese mainland companies are traded in yuan on the Shanghai and Shenzhen stock exchanges.
Meanwhile, large global asset management institutions such as BlackRock and Franklin Templeton have conducted frequent research on A-share companies, carrying out in-depth site visits to firms in the technology innovation and manufacturing sectors.
These new developments suggest that international investors are re-evaluating the investment value of Chinese assets. Against the backdrop of an uneven global economic recovery and persistent inflation and interest rate volatility in major developed economies, China's A-share market, supported by relatively attractive valuations, comprehensive industrial supply chains and ongoing industrial upgrading, is emerging as a significant component of global investment portfolios that cannot be overlooked.
Increasing numbers of overseas institutions are finding that the overall valuation of A-share stocks is highly attractive, offering a considerable advantage in terms of value for money compared with major overseas markets. JP Morgan and UBS note in their research reports that the A-share market has already shed a large amount of risk. The valuations of major indices remain historically low, while earnings are entering an early-cycle recovery phase, creating conditions for an upward trend in the market.
Foreign institutions' current research efforts are focused on sectors related to China's new quality productive forces, the term for economic drivers that make use of cutting-edge technologies such as AI, big data, new energy and innovative drugs. Goldman Sachs highlighted in its report the promising AI industrial chain in China, noting that the country is constructing a complete AI ecosystem spanning computing power, large language models and application layers. In their research, foreign institutions are focusing on corporate investment in research and development (R&D), technological barriers and progress in domestic substitution, seeking out high-end, innovation-driven small and medium-sized enterprises, as well as leaders within segmented industries, including new energy, lithium-ion batteries, semiconductors and innovative drugs.
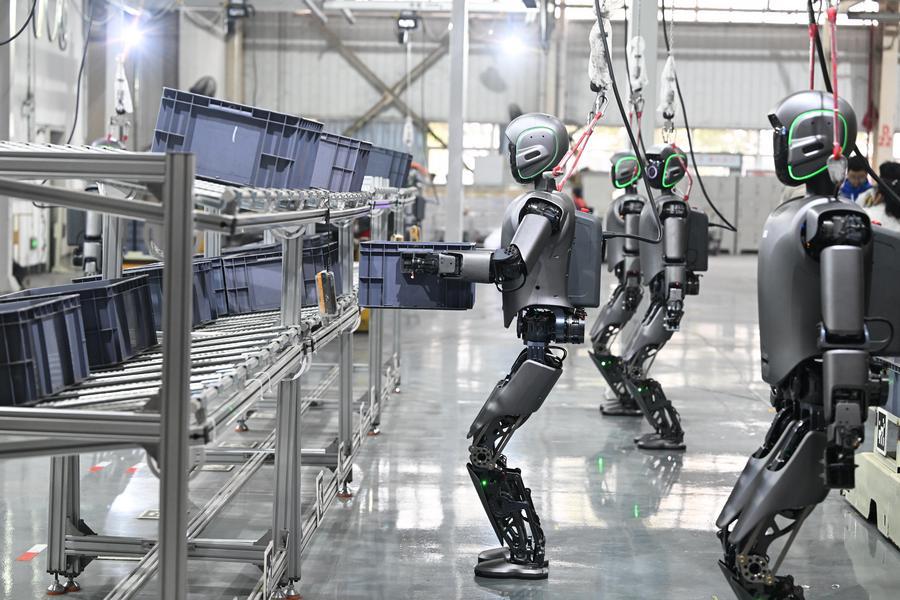
While valuation may serve as an immediate factor in attracting capital in the short term, China's complete industrial system and ongoing industrial upgrading are the fundamental conditions inspiring foreign investors' long-term confidence in Chinese assets. China has the world's largest and most complete industrial chain, extending from raw materials and basic components to the manufacturing of end-use products. This robust industrial ecosystem enables the country to continuously foster enterprises with global competitiveness, representing an advantage that many other economies find difficult to replicate. In the long run, China's progress in industrial upgrading, development of new quality productive forces and pursuing high-quality growth will continuously give rise to more enterprises with global competitiveness, thereby steadily stimulating the long-term investment value of the A-share market.
The concept of "new quality productive forces" refers to the shift toward innovation-driven growth, technological advancement and high-quality development in different sectors of the economy.
From a deeper perspective, increased research interest by foreign institutions and their positive outlook on Chinese assets also reflect that China's capital market is continuing to open wider to the outside world. As programs such as Shanghai-Hong Kong Stock Connect, Shenzhen-Hong Kong Stock Connect and the Qualified Foreign Institutional Investor program are continuously improved, cross-border investment channels are becoming easier to access. When international investors conduct research in China, it serves as a two-way exchange: Foreign investors gain firsthand insight into the development of Chinese enterprises and a better understanding of China's economic transformation, thereby reducing information asymmetry.
China is the world's second largest economy and its A-share market exhibits relatively low correlation with developed stock markets in the United States and elsewhere. This gives investors an option to diversify global portfolios and hedge against volatility in other markets. At a time when high inflation and high interest rates in some developed economies have yet to change, China maintains moderate inflation and has a highly resilient macroeconomy. Such stability is a hard-to-find asset in the global market.
Many foreign institutions have stated in their reports that the industrial clusters China has developed in areas including green transition, the digital economy and advanced manufacturing have placed the country in a proactive position amid the restructuring of global supply chains, and this structural advantage may not be replaced in the short term. It is foreseeable that as the institutional opening up of China's capital market steadily continues, the weight of Chinese assets in global portfolios will continue to rise.